Loan Comparison
Line up the dodgy offers side by side. The cheapest one gets the gold star — the rest can get stuffed.
Strong position — you should qualify for most mainstream lenders.
Don't know your score? Check free via Equifax or Credit Savvy.
The Full Damage — Side By Side
Check the final deal before you sign
Found the cheapest loan? Now plug the winner into the Fair Deal Checker to make sure the car price stacks up too.
Valuations here are based loosely on Redbook data — treat them as a solid ballpark, not gospel. Always cross-check before you sign anything.
How to Use the Loan Comparison
Choosing between two car loans shouldn't feel like picking which foot to stub. The Loan Comparison tool puts two loans side by side so you can see exactly which one costs you less.
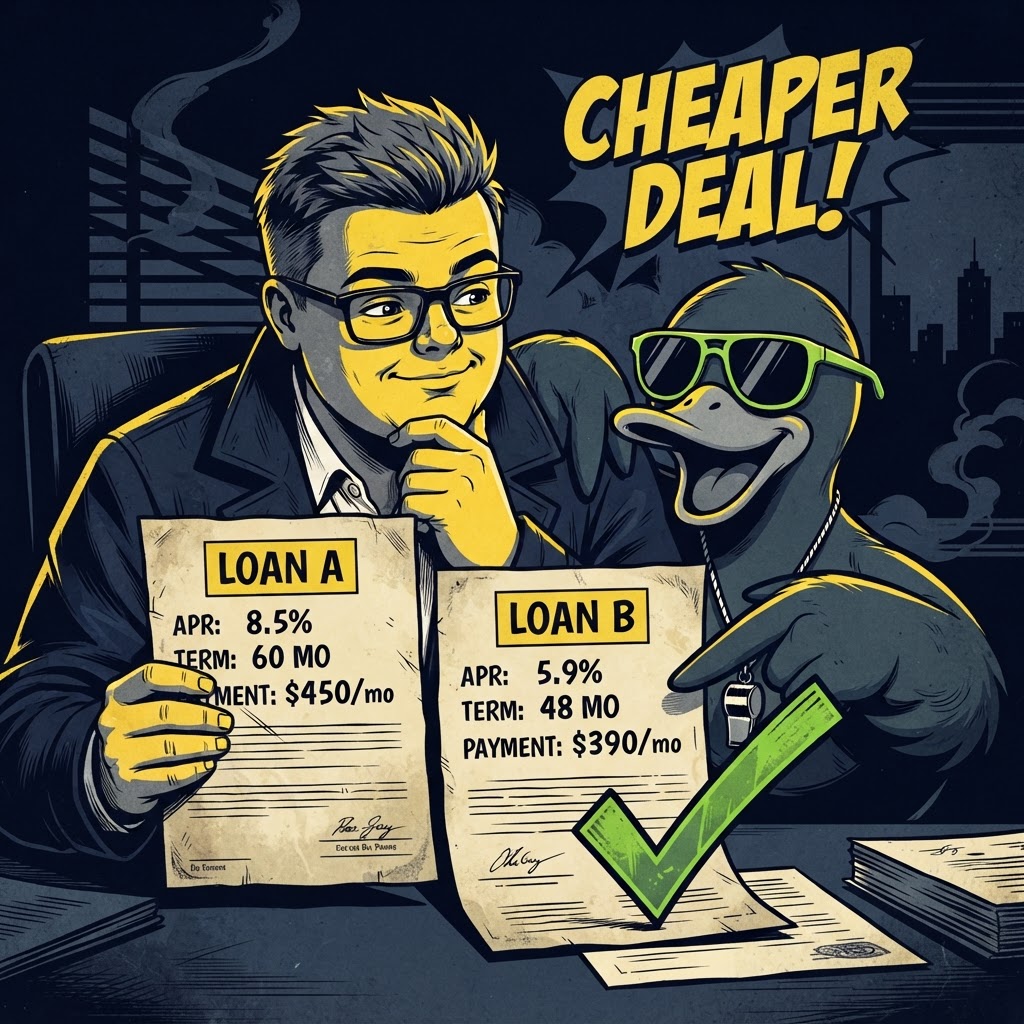
Here's how to use it:
- 1Enter Loan A details — this could be the dealer's finance offer, your bank's quote, or any loan you're considering. Pop in the loan amount, interest rate, term, fees, and balloon if applicable.
- 2Enter Loan B details — same thing for the second loan you're comparing against.
- 3Hit compare — you'll see both loans broken down side by side: weekly repayments, total interest, total cost, and balloon payment if applicable.
- 4Check the verdict — the tool highlights which loan costs you less overall, not just which has the lower weekly repayment.
The Duck wants you to know: the loan with the lower weekly repayment is NOT always the cheaper loan. A 7-year loan at 9% might cost less per week than a 3-year loan at 6%, but you'll pay thousands more in interest by the end.
Pro tip from The Guy: Always compare the TOTAL cost, not just the weekly number. That's the number the dealer doesn't want you looking at.
FAQ
40+ lenders · 15+ years experience · Cost-effective finance, quickly